An accepted offer is a milestone, not the finish line. Between acceptance and settlement, the buyer's inspection and the lender's appraisal are the two steps most likely to shake a deal loose. Here's how we manage the seller's side of the post-acceptance due diligence, respond to repair requests strategically, and defend the appraisal so your sale reaches the closing table.
The post-acceptation timeline.
Once your offer is accepted, several clocks start on the buyer's side: the inspection contingency (typically 7–14 days), the appraisal (ordered by the buyer's lender within the first two weeks), and the financing contingency or loan commitment (usually 21–30 days). Each is a deadline where the deal can stall or fall through. We track every deadline, coordinate with the buyer's agent, and keep the process moving so no one misses a date that could put the home back on the market.
Preparing for the home inspection.
The buyer's home inspector will spend 2–3 hours evaluating the home's major systems: roof, exterior, foundation, structure, heating and cooling, plumbing, electrical, insulation, and appliances. We prepare the home to be inspected: ensure access to the attic, basement, crawl spaces, electrical panel, and mechanicals; replace any burned-out bulbs (an inspector notes non-working lights); and make sure the utilities are on. A home that's accessible and ready inspects more smoothly and surfaces fewer red herrings. We also remind you to be away during the inspection, as the buyer and their inspector are more comfortable — and more focused — without the seller present.
Anticipating what the inspection may surface.
Because we've already walked the home with you, disclosed known issues, and priced the home to reflect its condition, the inspection shouldn't surface major surprises — but it may surface items we anticipated. In Central PA's older housing stock, common findings include: aging mechanicals (a 20-year-old furnace, a 12-year-old water heater), galvanized or lead water lines in pre-1950 homes, knob-and-tube wiring in pre-1940 homes, foundation settling or efflorescence, older roofs nearing end of life, and radon (common in Central PA's geology). We anticipated these in our prep and pricing, so we're prepared to respond calmly rather than react in panic.
Responding to the buyer's repair request.
After the inspection, the buyer may submit a repair request or ask for a credit. We help you respond strategically. We categorize the requests: safety items (a missing GFCI, a loose railing) that are reasonable to address; major system issues (a failing roof, a cracked heat exchanger) that may warrant a credit or a price adjustment; and cosmetic or normal-age items (a water heater near end of life, minor settling) that are part of owning an older home and don't warrant a seller concession. We don't agree to a 20-item repair list reflexively, and we don't dismiss a real safety issue. We present a clear, reasonable response that keeps the deal alive while protecting your equity.
The repair credit versus the repair.
Often a repair credit (a dollar amount credited to the buyer at closing) is cleaner than the seller making repairs — it avoids the scheduling, quality, and warranty complications of a seller-managed repair, and it lets the buyer handle the work after closing. We've negotiated many repair credits and know how to size them fairly. A $1,500 credit toward a near-end-of-life water heater is often more agreeable to both sides than the seller rushing to replace it before settlement. We'll advise when a credit serves you better than a repair.
Specialized inspections that may arise.
Depending on the property, the buyer may order specialized inspections: a radon test (radon is common in Central PA; a mitigation system runs $1,200–$2,500), a wood-destroying-insect (termite) inspection, a sewer line scope (older homes can have failing clay or Orangeburg lines), a well-water test, or a chimney inspection. We anticipated these in our prep and disclosure, so we're prepared. If a specialized test surfaces an issue, we negotiate a fair resolution — often a credit or, for a safety item, a repair before closing.
The appraisal and defending your sale price.
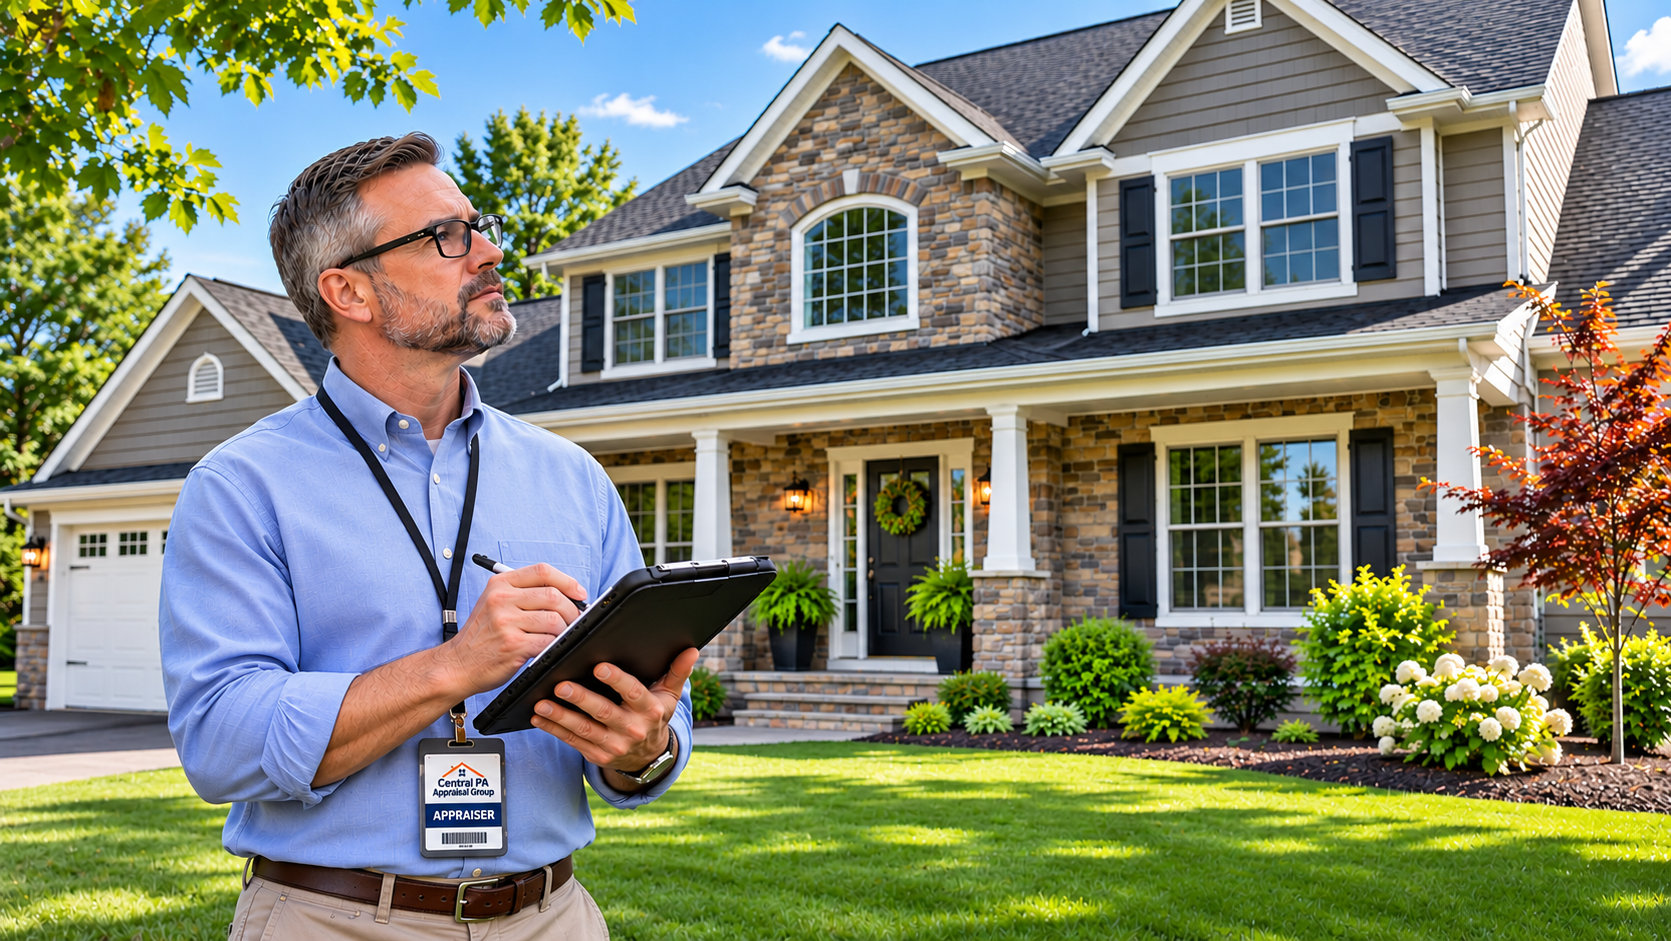
The buyer's lender orders an appraisal to confirm the home's value supports the loan. The appraiser uses the same closed-sale comps we used in our CMA, inspects the home's condition, and produces a valuation. If the appraisal comes in at or above the contract price, the deal proceeds smoothly. If it comes in low, the buyer may need to bridge the gap in cash, the price may be renegotiated, or the buyer may walk. We defend the appraisal by providing the appraiser with our comparable sales analysis, details of the home's features and updates, and any relevant neighborhood data — a well-supported appraisal is more likely to come in at value. We meet the appraiser at the property when possible to walk them through the home's strengths.
What to do if the appraisal comes in low.
A low appraisal isn't the end of the deal — it's a moment to negotiate. We have options: the buyer can make up the gap in cash (if they value the home and have the funds); we can renegotiate the price to the appraised value (if you're willing); the buyer can challenge the appraisal with additional comps (we help assemble them); or, if no resolution is possible, the buyer may walk and we relist. We've navigated appraisal gaps many times and know how to find the path that keeps the deal alive when both sides want it to. We also price realistically from the start — a well-supported list price is your best defense against a low appraisal.
Coordinating the vendors and deadlines.
Between acceptance and settlement, there's a stack of moving parts: the buyer's inspector, radon tester, and lender; the appraiser; the title company; the buyer's insurance agent; and both agents. We coordinate the seller's side and stay in sync with the buyer's agent so every deadline is met. A missed inspection deadline can let the buyer walk; a delayed appraisal can push settlement. We keep the process on track with proactive communication, because the settlement date is only firm if every step hits its mark.
Scenario: the inspection negotiation.
A buyer's inspection on a 1965 Mechanicsburg colonial surfaces a 22-year-old furnace, a minor roof leak around a chimney flashing, and a radon test at 6 pCi/L. The buyer requests a new furnace, a roof repair, and a radon mitigation system — roughly $9,000 in work. We respond strategically: we agree to the roof flashing repair (a real issue, $400), we offer a $1,200 radon mitigation credit (the standard fix), and we decline the furnace replacement (a 22-year-old furnace is near end of life but functioning, and was reflected in the price and disclosed). The buyer accepts, the deal stays alive, and you protect your equity. This is the difference between a strategic response and a reflexive yes.
Scenario: the low appraisal.
A Hershey home sells for $520,000; the appraisal comes in at $505,000 — a $15,000 gap. The buyer has an appraisal contingency. We provide the appraiser with three recent closed comps that support a higher value and details of the home's premium features, but the appraiser holds at $505,000. We negotiate: the seller agrees to reduce the price to $512,000 and the buyer bridges the remaining $7,000 in cash. Both sides give a little, the deal closes, and neither party walks away. An appraisal gap is a negotiation, not a failure — and we know how to find the middle.
The path from acceptance to a clean closing.
The inspection and appraisal are the two highest-risk steps after acceptance, and managing them well is what gets a deal to the closing table. We anticipate issues, respond strategically, defend the appraisal, and coordinate every deadline — so the terms we negotiated at acceptance are the terms you sign at settlement. Ready to sell with a team that protects the deal after acceptance? Aaron Rissinger and Josh Krevsky — Living in Central PA Team | Iron Valley Real Estate of Central PA — 717-REALTOR (717-732-5867).
Key Takeaways
- Several clocks start at acceptance — we track every inspection, appraisal, and financing deadline
- Prepare the home to be inspected: access, utilities, and your absence help it go smoothly
- Anticipate common Central PA findings: old mechanicals, galvanized lines, radon, settling
- Respond to repair requests strategically — address safety, credit major items, decline cosmetics
- A repair credit is often cleaner than a seller-managed repair
- We defend the appraisal with our comparable sales analysis and the home's features
- A low appraisal is a negotiation, not a failure — we find the path that keeps the deal alive
- We coordinate every vendor and deadline so the settlement date stays firm