When the offers come in, the real work begins. The best offer isn't always the one with the highest price — it's the one with the strongest combination of price, terms, financing, and likelihood of closing. Whether your home is in Harrisburg, Camp Hill, Mechanicsburg, Carlisle, Hershey, or Lancaster, here's how we evaluate every offer on your Central PA home, how we negotiate to protect your equity, and how we keep the deal alive from acceptance to settlement.
We don't just look at the price.
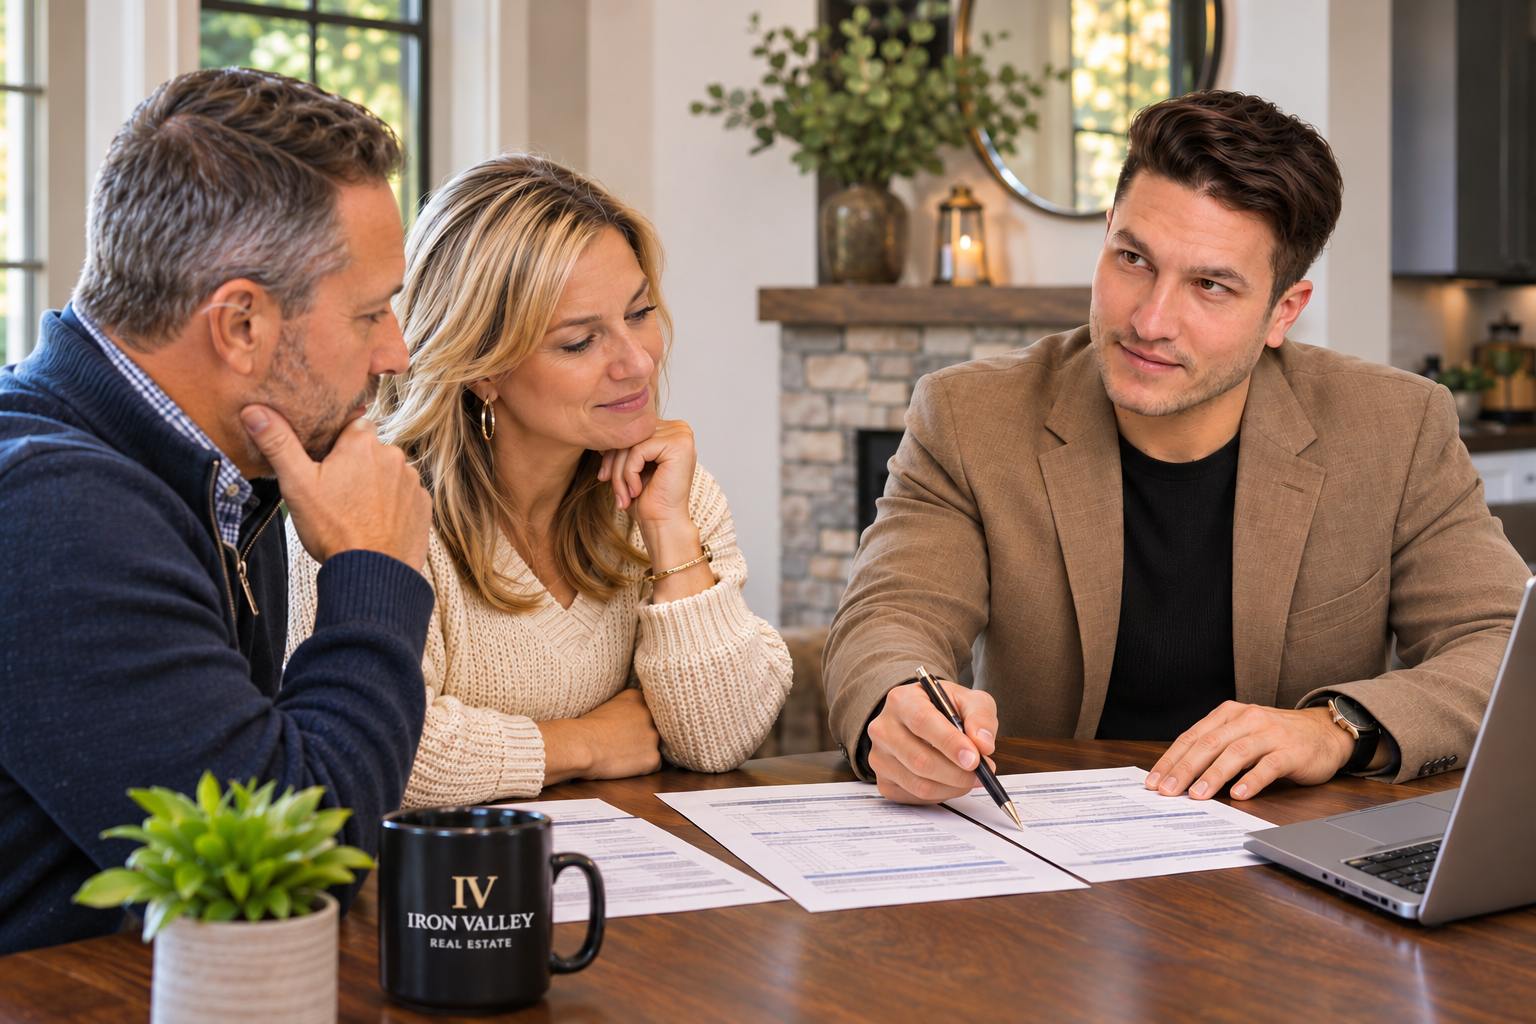
When an offer arrives, we evaluate it on multiple dimensions: the offered price relative to the supported value and the list price; the financing type and strength (conventional, FHA, VA, or cash); the buyer's pre-approval verification; the earnest money amount; the contingencies (inspection, appraisal, financing, home-sale); the proposed settlement timeline; and any concessions or requests (closing-cost help, a rent-back, included items). A high offer with shaky financing and a long contingency list can be riskier than a slightly lower offer with clean terms and verified cash. We evaluate the strongest overall package, not just the headline number.
Financing strength and the likelihood of closing.
The most important question behind any offer is: will this deal actually close? A conventional loan with 20% down and a verified pre-approval from a local lender signals a strong, likely-to-close deal. An FHA loan with 3.5% down is fully legitimate but can be perceived as riskier in a competitive appraisal environment. A cash offer eliminates financing risk entirely — but a cash buyer should still include an appraisal contingency if they want the protection. We've seen sellers take our client's offer over a higher one because our terms were cleaner and our financing was verifiable. We assess each offer's closing risk honestly and advise accordingly.
The inspection contingency and how to handle it.
The inspection contingency is the buyer's right to inspect the home and renegotiate or walk based on the findings. In Central PA, where much of our inventory is decades old, inspections routinely surface items. We anticipate this: we've already disclosed known issues, we've priced the home to reflect its condition, and we're prepared to respond to repair requests strategically. Options include addressing safety items, offering a repair credit, or holding firm on an as-is-priced home. We've negotiated repair credits, price reductions, and seller-paid home warranties more times than we can count — and we've also advised sellers to hold firm when a buyer's request was unreasonable. The goal is terms that protect your equity while keeping the buyer engaged.
The appraisal and your sale price.
If the buyer is financing, their lender will order an appraisal to confirm the home is worth the agreed price. If the appraisal comes in at or above the contract price, the deal proceeds. If it comes in low, the buyer may need to make up the gap in cash, the price may need to be renegotiated, or the buyer may walk (if they have an appraisal contingency). We help defend the appraisal by providing the appraiser with our comparable sales analysis and any relevant data about the home's features — a well-supported appraisal is more likely to come in at value. We've also navigated appraisal gaps with buyers who valued the home enough to bridge the difference. We monitor the appraisal and help you respond if there's a gap.
Earnest money as a signal.
Earnest money — the buyer's deposit in escrow — signals commitment. A small earnest deposit reads as a buyer who isn't very committed; a larger one (1–3% of the price) reads as a serious buyer with skin in the game. In a multiple-offer situation, we may counsel buyers to strengthen their earnest money, and as sellers' agents we weigh earnest money as one indicator of the offer's strength. The earnest money becomes non-refundable (in most cases) once the buyer clears contingencies, so it's also a measure of how far the buyer has committed.
Settlement timeline and flexibility.
The proposed settlement date matters. A buyer who needs 45 days may fit your timeline; one who needs 75 days may not. Conversely, a buyer who can close quickly may be ideal if you've already found your next home. We also consider rent-back or post-settlement possession if you need time after closing to find your next home — a flexible settlement timeline can be a negotiating lever that benefits both sides. We match the timeline to your needs and use flexibility as a term.
Multiple offers: creating competitive energy.
When multiple offers arrive — which happens with well-priced, well-presented homes in desirable areas — we manage the process to maximize your outcome. We set a deadline for best-and-final offers, we ensure every buyer has a fair shot, and we evaluate the resulting offers on the full package, not just price. Multiple offers create competitive energy that can push the final price above the list and produce cleaner terms. We've managed many multiple-offer situations and know how to run them fairly, transparently, and to your advantage.
Counteroffers and the art of the response.
When an offer isn't quite right, we counter — but we counter strategically, not reflexively. We read the offer for what it tells us about the buyer's priorities: are they holding firm on price because they need the equity, or are they flexible on price in exchange for a faster close? We've negotiated final prices by offering a higher number in exchange for the seller covering closing costs, by adjusting the settlement date, and by removing a contingency the buyer found annoying. Every negotiation is a conversation about what each side values most, and we represent your values in it.
Scenario: the multiple offer.
A well-priced Camp Hill colonial draws three offers in the first weekend. Offer A is $345,000 with FHA financing and a long inspection contingency. Offer B is $342,000 with conventional 20% down, a verified pre-approval, and a clean inspection contingency. Offer C is $339,000 cash, as-is, 14-day close. We evaluate: Offer A has the highest price but the most closing risk; Offer B is the strongest overall package; Offer C is the fastest and cleanest but lowest. We present the analysis, counter Offer B to $346,000 with a 35-day close that fits your timeline, and it's accepted. The home sells for above the supported value with clean terms and a high likelihood of closing. This is what skilled offer evaluation and negotiation delivers.
Scenario: the lowball.
A buyer submits an offer $30,000 under asking with a long list of repair demands, clearly testing whether you'll panic. We don't. We respond with a firm counter at or near list price, backed by the comparable sales data, and we let the buyer decide. Often a lowballer walks — and that's fine, because a deal on those terms would have cost you. Sometimes they come back with a reasonable offer once they see you're represented by an agent who knows the data. Either way, we protect your equity rather than capitulating to pressure.
Keeping the deal alive after acceptance.
An accepted offer is a milestone, not the finish line. Between acceptance and settlement, the inspection, appraisal, and financing all have to line up. We manage every deadline, respond to issues promptly, and keep the buyer's side moving. If the inspection surfaces a real issue, we negotiate a fair resolution. If the appraisal comes in low, we help bridge the gap. If the buyer's financing hits a snag, we coordinate with the lender. Our job is to get you to the settlement table with the terms we negotiated — and we do. Ready to negotiate from a position of strength? Aaron Rissinger and Josh Krevsky — Living in Central PA Team | Iron Valley Real Estate of Central PA — 717-REALTOR (717-732-5867) — your Central PA real estate agents for offer negotiation across Harrisburg, Camp Hill, Mechanicsburg, Carlisle, Hershey, Lancaster, and the 717 area.
Key Takeaways
- The best offer is the strongest package — price, terms, financing, and closing likelihood
- We assess each offer's closing risk honestly, not just the headline number
- Anticipate the inspection; respond to repair requests strategically, not reflexively
- We defend the appraisal with our comparable sales analysis
- Earnest money signals commitment; settlement flexibility is a negotiating lever
- In multiple offers, we run a fair, transparent best-and-final process
- Counteroffers are strategic — we read the buyer's priorities, not just the price
- We keep the deal alive from acceptance to settlement, managing every deadline
- Work with a Central PA real estate agent who negotiates firmly but fairly
- Negotiate offers on your home in Harrisburg, Camp Hill, Mechanicsburg, Carlisle & Hershey