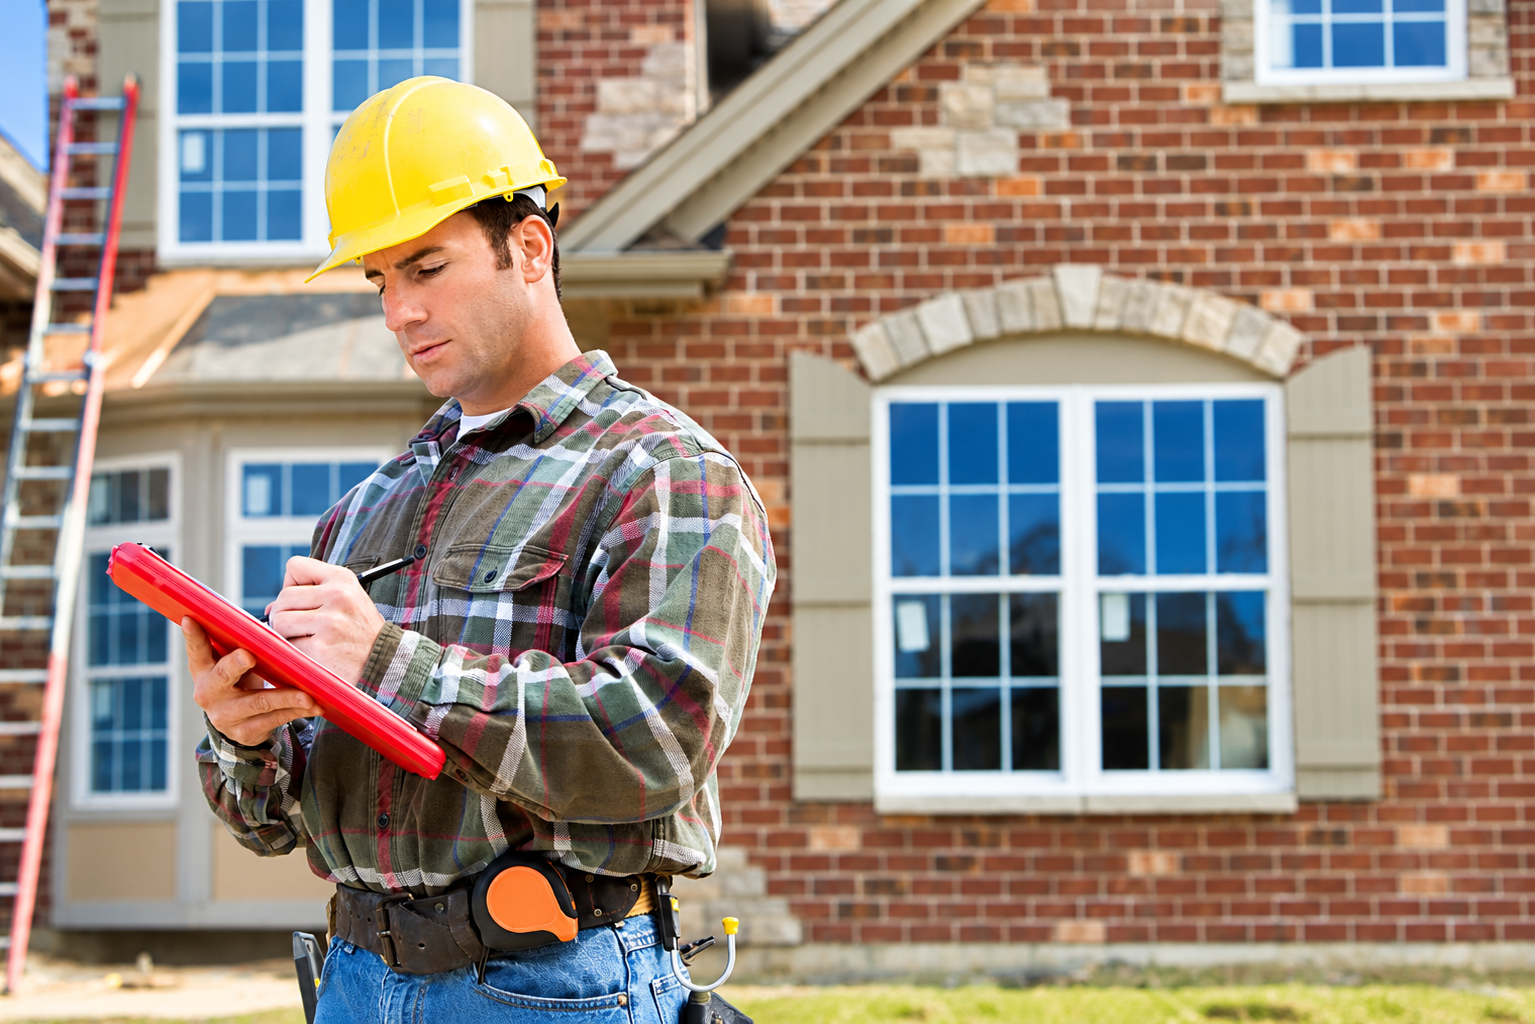
Professional home inspection in Central PA — reviewing exterior, roofing, mechanicals, and structural components before settlement.
Navigating mortgage financing and loan underwriting — reviewing loan terms, closing costs, and lender timelines.
Once your offer is accepted, you enter the most technical phase of the transaction: due diligence. This is where the inspection reveals what you're actually buying, the appraisal protects the lender's (and your) investment, and your financing gets underwritten and cleared. In Central PA, where much of our inventory in Harrisburg, Camp Hill, Mechanicsburg, Carlisle, and Hershey is decades old and the financing timeline has to line up with the inspection and appraisal deadlines, this phase is where deals either close cleanly or fall apart. Here's how we manage it.
The timeline starts the moment you're under contract.
When the seller accepts your offer, several clocks start simultaneously. The inspection contingency typically runs 7–14 days from acceptance; the appraisal is ordered by your lender and scheduled within the first two weeks; the financing contingency (or loan commitment) is usually due 21–30 days out; and settlement is scheduled for 30–60 days from acceptance. Every one of these deadlines is a date you can lose the deal on if you miss it — and a date the seller can use to put the home back on the market if you fail to perform. We manage this timeline for you, but we need you responsive: a lender who can't reach you for three days during underwriting can blow a closing.
Order the inspection immediately — and use the right inspector.
The home inspection is the single most important due-diligence step in Central PA, where a large share of homes in Camp Hill, Mechanicsburg, Lemoyne, and the Harrisburg boroughs are 60–80 years old. We schedule the inspection within 24–48 hours of acceptance, because the contingency clock is short and the inspector's schedule fills up. We work with licensed, experienced inspectors who know Central PA housing stock — the galvanized water lines, the knob-and-tube wiring, the stone foundations, the settling that's normal for a 1920s colonial versus the structural movement that's a problem. A generic inspector from an online directory may miss region-specific issues. We'll recommend inspectors we've worked with for years, or work with one you choose — either way, we attend the inspection with you.
What the inspection covers — and what it doesn't.
A standard home inspection covers the major systems: roof, exterior, foundation, structure, heating and cooling, plumbing, electrical, insulation and ventilation, interior, and appliances. It does not, by default, cover everything. Specialized inspections we may recommend based on the property: a radon test (radon is common in Central PA's geology and a mitigation system runs $1,200–$2,500), a wood-destroying-insect (termite) inspection, a sewer line scope (older homes can have clay or Orangeburg sewer lines that are failing), a mold assessment, a well-water test (for properties on well water), a chimney inspection, and an HVAC system evaluation for older units. Each of these is a few hundred dollars and can save you thousands. We'll tell you which are worth it for the specific home.
Read the inspection honestly.
The inspection report will be 30–60 pages long with photos, and it will list dozens of items. The trap is either treating every item as a deal-breaker (no home is perfect, especially a 70-year-old one) or dismissing the whole report because 'the inspector was being dramatic.' We help you read it in three buckets: safety items (a missing GFCI outlet near water, a loose deck railing, an unsafe electrical panel) that should be addressed; major system issues (a failing roof, a cracked heat exchanger, a compromised foundation) that may be worth renegotiating; and normal maintenance and age items (a water heater near end of life, minor settling, cosmetic cracks) that are part of owning an older home. The first two are negotiation points; the third is a future budget.
Negotiate from the inspection, not from emotion.
Once the inspection is complete, we sit down and decide what to ask for. We don't ask for everything — a seller who gets a 20-item repair list often says no to all of it. We prioritize: the safety item the seller should fix, the major system with real cost, and the one or two items that matter most to you. We present it as a clear, reasonable request: 'Here's what the inspection found, here's what we'd like addressed or credited, here's why.' Most sellers respond reasonably because they want to close. If a seller refuses to address a real safety or structural issue, we talk with you about walking — the inspection contingency exists to protect you, and using it is not 'being difficult.'
The appraisal protects the lender's investment — and yours.
Your lender orders an appraisal to confirm the home is worth what you've agreed to pay, because the lender won't lend more than the home is worth. In a hot market, a home can appraise below the contract price — and when that happens, you have a few options: renegotiate the price down to the appraised value, pay the difference in cash, or walk away (if you have an appraisal contingency). We've seen appraisals come in low in premium markets like Hershey and in rapid-appreciation situations; we've also seen them come in exactly at contract in well-priced Camp Hill and Mechanicsburg sales. We monitor the appraisal and help you respond if there's a gap. We also help your lender find the right comps — a well-supported appraisal is more likely to come in at value.
Financing: keep your lender moving.
The financing contingency is the deadline by which your lender must issue a clear-to-close (or commitment) letter, confirming your loan is fully underwritten and ready. To hit it, your lender needs documentation from you — updated pay stubs, bank statements, verification of large deposits, explanation of any credit inquiries, and sometimes a letter about a specific charge. We stay in touch with your lender weekly and flag anything that's slowing down underwriting, but we need you responsive to their document requests within 24 hours. The most common cause of a delayed closing is a buyer who went silent on their lender during underwriting.
Don't make financing mistakes between acceptance and settlement.
Once you're under contract, your credit is effectively frozen for the transaction. The moves that can derail a loan: opening a new credit card, financing furniture for the new house, making a large deposit your lender can't source, quitting or changing jobs, closing an old credit account, or missing a payment. We tell every buyer the same thing the moment they're under contract: don't open credit, don't move money, don't change jobs, and don't buy furniture on credit until we're at the closing table. We've seen a single new credit inquiry delay a closing by a week; we've seen a new car loan sink a deal entirely. Protect your credit like it's part of the transaction — because it is.
Coordinate the vendors so nothing slips.
Between acceptance and settlement, there's a stack of moving parts: the inspector, the radon tester, your lender, the title company, the appraiser, your insurance agent, the seller's agent, and the seller. We coordinate all of it. We schedule the inspections, confirm the appraisal is ordered, ensure the title work is moving, remind you to shop and bind homeowners insurance (your lender requires it), and keep the seller's side informed so no one's surprised by a deadline. The settlement date is only firm if every vendor hits their step on time — and that's our job to manage.
Scenario: the older Camp Hill home.
A buyer goes under contract on a 1948 Camp Hill colonial. The inspection reveals galvanized water lines (a $6,000–$10,000 whole-house repipe), knob-and-tube wiring in part of the home (an $8,000–$15,000 rewire), a 22-year-old furnace (near end of life), and minor foundation settling that's normal for the age. The galvanized and the wiring are real items; the furnace is a future budget; the settling is noted but not structural. We negotiate a $10,000 seller credit toward the repipe and rewire, the seller agrees, and the buyer proceeds with a clear plan and budget for the furnace over the next few years. Without an inspection, this buyer would have inherited $20,000+ in near-term repairs with no credit. With one, the deal still closed — at a price that reflected the real cost of the home.
Scenario: the new construction appraisal.
A buyer goes under contract on a new build in a Hampden Township development. There are no older-home inspection issues, but the appraisal is the risk: new construction in a developing area may have limited closed comps, which can make the appraisal come in below contract if the builder has been raising prices faster than the market has recorded sales. We work with the lender to provide the builder's recent closed sales and the comparable new construction in the area, and we negotiate with the builder for an appraisal gap coverage clause before we sign. Due diligence on new construction looks different — it's about the appraisal, the builder's warranty, and the final walkthrough punch list — but it's no less important.
Scenario: the radon surprise.
A buyer goes under contract on a well-maintained Mechanicsburg home. The standard inspection is clean, but the radon test comes back elevated — which is common in Central PA, where the geology produces higher radon levels in many areas. A mitigation system is $1,200–$2,500. We negotiate the seller to install one before settlement or credit the cost at closing, the home is safe, and the deal closes. A buyer who skipped the radon test to save $150 would have discovered the issue months later — and paid for it out of pocket. The due-diligence phase is exactly the time to find these.
The final walkthrough and settlement.
A few days before settlement, we do a final walkthrough of the home to confirm it's in the agreed condition, the repairs from the inspection were completed, the seller left what they agreed to leave, and nothing has changed since you last saw it. Then we go to settlement — the closing table, where you sign the documents, your loan funds, and you get your keys. We attend settlement with you, walk you through the paperwork, and make sure the numbers match the offer and the inspection credits. The due-diligence phase is the unglamorous part of buying a home — and it's the part that decides whether you close on the home you chose or on a surprise. Ready to navigate inspections and financing with a team that manages every deadline? Aaron Rissinger and Josh Krevsky — Living in Central PA Team | Iron Valley Real Estate of Central PA — 717-REALTOR (717-732-5867) — your Central PA real estate agents for home inspections, appraisals, and financing across Harrisburg, Camp Hill, Mechanicsburg, Carlisle, Hershey, Lancaster, and the 717 area.
Key Takeaways
- Several clocks start at acceptance — we manage the inspection, appraisal, financing, and settlement deadlines
- Order the inspection within 24–48 hours; use an inspector who knows Central PA housing stock
- Specialized tests (radon, sewer scope, termite, well) are cheap insurance on older homes
- Read the report in three buckets: safety, major systems, and normal age — don't over- or under-react
- The appraisal protects your investment — we help your lender find the right comps
- Stay responsive to your lender; the most common closing delay is a buyer who went silent
- Don't open credit, move money, or change jobs between acceptance and settlement
- We coordinate every vendor so the settlement date stays firm
- Work with a Central PA real estate agent who manages inspections & financing deadlines
- Radon is common in Central PA geology — always test before closing